BILL Spend & Expense (Divvy)

- 555.00 Reviews
- 4.5
- Downloads
- 100,000+
Our take on BILL Spend & Expense (Divvy) from Appgk
I tested BILL Spend & Expense as a business finance app, and my first impression was that it is built for teams that need more control over company spending than a shared card and a spreadsheet can provide. Its focus is straightforward: corporate cards and expense management in one mobile workflow. That sounds simple, but the practical value appears when several people spend on behalf of the same organization and someone needs a consistent way to understand those purchases afterward.
BILL Spend & Expense is free, aimed at Everyone, and developed by Bill.com Inc. It has reached over one hundred thousand installs, with a 4.5 average from around four thousand ratings and more than five hundred written reviews. Those figures suggest a product with an established user base, although they do not replace checking whether its approach fits the way your own business handles approvals, records, and employee spending.
How the everyday spending workflow feels
The most useful way to think about this app is not as a general-purpose personal budgeting tool. I would place it firmly in the business category, where the important question is not simply “How much did I spend?” but “Who spent it, for what business reason, and how should the company review it?” That distinction shapes the whole experience.
A normal day might look like this: an employee pays for a client lunch, a software subscription, or travel connected with work. Instead of leaving the transaction for the end of the month, the employee can use the company’s spending process to keep the purchase connected to the business record. A manager then has a clearer basis for reviewing the expense, while the finance team has less detective work to do later.
Best Parts of BILL Spend & Expense (Divvy)
Things to Keep in Mind About BILL Spend & Expense (Divvy)
That workflow is especially helpful when spending is distributed across a small team. A single owner may remember every purchase, but memory becomes unreliable as soon as several employees use company funds in different places. The app’s value comes from making those purchases part of a repeatable routine rather than a collection of messages, receipts, and last-minute explanations.
I also like the separation between the card activity itself and the expense-management task around it. A corporate card can show that money left the account, but that alone does not explain the business context. Expense management adds the human details that make a transaction easier to review. In practice, that can reduce the back-and-forth that often happens when a finance person asks what an unfamiliar charge was for.
News and Features Related to BILL Spend & Expense (Divvy)

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Still, this is not an app I would recommend simply because someone wants to monitor personal spending from a phone. Its language, purpose, and workflow make more sense for an organization with shared financial responsibility. A freelancer might find it useful if business purchases are frequent and need structure, but a personal finance app may be quicker for someone who only wants household categories and a simple monthly overview.
Where the baseline routine succeeds
The strongest routine is to deal with a purchase while it is still fresh. When an employee waits until the end of a billing cycle, small details disappear first: the names of attendees, the reason for a purchase, or which project benefited from it. A disciplined user treats the app as part of the spending moment, not merely as a place to inspect old transactions.
Don't want to read the full review?
That habit also helps managers. Reviewing a steady stream of understandable expenses is easier than receiving a large batch with vague descriptions. The app cannot create good information when the user supplies none, so the quality of the final record depends partly on how consistently the team completes its side of the process.
For a business owner, the practical benefit is visibility without personally asking every employee for an update. For an employee, the benefit is having a clear place to handle company purchases instead of wondering whether a receipt belongs in email, a chat thread, or a shared folder. For a finance worker, the benefit is a more organized trail to examine when reconciling spending.
Screenshots
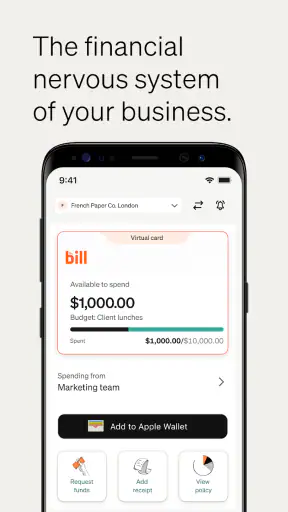
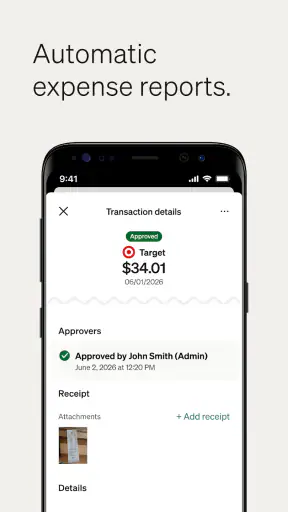
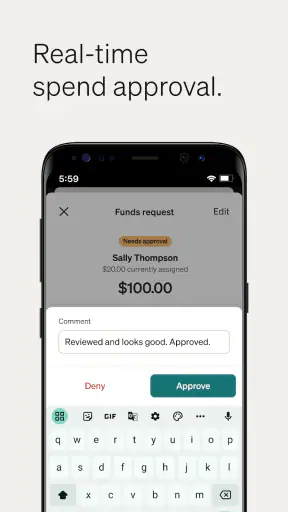
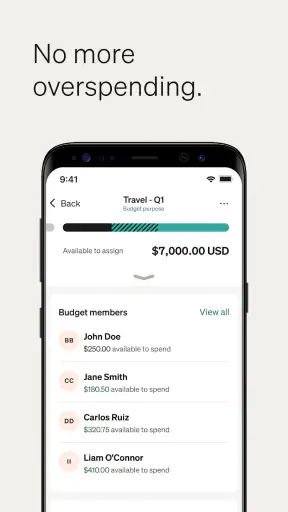
There is a trade-off, though. Adding structure always asks something from the user. People who resist entering context or following a company process may see the app as an extra step. That is not a flaw unique to this product; it is the cost of turning informal spending into information that another person can trust.
Settings and habits worth checking early
Before inviting a whole team into the workflow, I would spend time reviewing the organization’s spending rules and deciding what information employees are expected to provide. The most important setup is not a decorative preference. It is agreeing on the company’s definition of a complete expense record.
For example, decide whether your team needs a short business purpose, a project reference, a client name, or another internal detail. Then make that expectation easy to explain. If every employee uses a different level of detail, managers will still need to ask follow-up questions even though the transactions are in one system.
I would also test the process with a small group before making it the default for everyone. Use several realistic purchases: a recurring subscription, a travel expense, and a shared meal. This reveals where people hesitate and whether the approval routine matches the way the business actually operates. A short pilot is more useful than assuming that a clean interface automatically produces clean records.
Another worthwhile check is the boundary between card spending and other expenses. Not every business purchase will necessarily follow the same path. Your team should know what belongs in the corporate-card workflow and what requires a separate process. Without that distinction, employees may either duplicate information or leave gaps because they are unsure where a transaction belongs.
Device compatibility matters as well. The current version is 4.0.17 and requires iOS or Android 12 or later. That requirement is reasonable for many modern phones, but it can affect companies that keep older devices in circulation. I would confirm the operating-system situation before treating the app as a universal solution for a mixed fleet.
The Everyone content rating makes it broadly suitable from an age-classification perspective, but business suitability is a different question. A company still needs to consider its internal controls, employee roles, and accounting routine. An app can be easy to install and still require thoughtful decisions about who should use it and how spending should be reviewed.
Faster patterns for repeat users
Once the basic process is understood, speed comes from reducing decisions rather than rushing through them. I found that the best pattern is to make the same type of purchase follow the same sequence every time. Employees should not have to invent a new explanation style for each transaction.
A useful routine is to handle the expense immediately after the purchase, while the purpose is obvious, then leave the manager with only the review decision. This is faster than postponing everything and trying to reconstruct a week of spending in one sitting. It also makes unusual purchases stand out instead of being buried among many ordinary ones.
Recurring expenses deserve their own habit. If the same type of business charge appears regularly, the team should agree in advance on the description and business context that will make it recognizable. That does not mean copying careless notes forever; it means creating a consistent starting point and updating it when the purpose changes.
For managers, batching review time can be more efficient than interrupting work for every single notification. A predictable review window helps separate routine purchases from exceptions. The important distinction is that batching review should not become an excuse for employees to delay documenting the transaction itself.
Finance teams can also use a simple exception mindset: ordinary purchases should be easy to understand, while unusual amounts, unfamiliar merchants, or unclear purposes deserve closer attention. This approach makes the app more valuable than a passive list of charges because it turns review into a prioritization task.
One non-obvious advantage of a repeatable pattern is that it exposes training problems. If the same kind of transaction repeatedly arrives with missing context, the issue may not be individual carelessness. It may indicate that the company’s instructions are ambiguous. Reviewing patterns in the records can therefore improve the spending policy itself.
What experienced teams should not assume
It is tempting to believe that combining corporate cards with expense management will eliminate every finance headache. It will not. The app can organize the information people provide, but it cannot decide whether a purchase was wise, whether a policy is fair, or whether a manager is applying the rules consistently.
It is also important not to confuse visibility with automatic approval. Seeing a transaction quickly is useful, but a visible charge can still need explanation or review. Businesses should keep their own separation between an employee making a purchase and the person responsible for checking it.
Another limitation is that the app may feel excessive for a very small operation with only occasional business purchases. If one person owns the company card, makes every purchase, and already keeps reliable records, adding a dedicated workflow may introduce more administration than it removes. In that situation, a simpler accounting routine could be the better choice.
At the other end of the scale, larger organizations may need to examine how well the app fits their existing finance stack, approval structure, and reporting expectations. The corporate-card and expense-management combination is appealing, but no single mobile app should be assumed to replace every accounting or compliance process a complex organization already uses.
There is also a human limit. If employees see the app as surveillance rather than as a clear way to document legitimate business spending, adoption can suffer. A good rollout should explain the purpose of the process and show what information is expected. Otherwise, the organization may have technically centralized its expenses without improving the quality of its records.
Who will get the most from it
I think BILL Spend & Expense is best suited to small and growing businesses that have moved beyond informal reimbursement habits but do not want employees and finance staff working across disconnected tools. It is particularly relevant when multiple people spend company money and the business needs a shared view of those purchases.
It can also suit teams with frequent travel, client-related spending, or recurring operational purchases. These are the situations where forgotten receipts and vague explanations create repeated friction. A mobile-first process is useful because the employee is more likely to be near the transaction when the details are still available.
Owners and managers may appreciate the ability to establish a consistent spending rhythm without personally collecting every detail through email. Employees may appreciate having one recognizable place to handle company expenses. Finance staff may value the reduction in scattered records, provided the team actually follows the process.
I would be more cautious for someone looking for a personal expense tracker, a household budget, or a lightweight way to split dinner costs with friends. Those needs call for different priorities. This app is about organizational spending, so its structure makes more sense when there is a company behind the transaction and someone responsible for reviewing it.
How it compares with familiar alternatives
The usual alternative is a corporate card combined with email, spreadsheets, and a shared drive for receipts. That approach can work at the beginning, especially when one person knows every purchase. Its weakness appears as the team grows: information becomes scattered, naming conventions drift, and follow-up questions arrive long after the purchase.
BILL Spend & Expense offers a more unified direction by bringing the card and expense-management ideas closer together. The advantage is not necessarily that every task becomes effortless. The advantage is that the business can build one recognizable process instead of asking employees to remember several disconnected steps.
A traditional accounting platform may still be stronger for broad bookkeeping, tax preparation, or detailed financial reporting. I would view this app as a spending-control and expense-workflow choice rather than automatically treating it as a complete replacement for every accounting system. Businesses should choose the tool that matches the stage and complexity of their financial operation.
Manual reimbursement can remain preferable for teams that rarely issue company cards or want employees to use personal funds. That method gives the business a familiar approval trail, but it can also place a cash-flow burden on employees and create more work during reimbursement. The right choice depends on whether the company’s bigger problem is controlling card spending or processing repayments.
The meaningful comparison is therefore about workflow, not just feature count. If your main pain is scattered corporate-card activity, this app’s combined focus is relevant. If your main pain is full-scale accounting, payroll, or tax reporting, you may need a broader system alongside it or instead of it.
My verdict after building a repeatable routine
After looking at the app through the lens of daily use, I see BILL Spend & Expense as a practical business tool whose success depends heavily on the habits around it. The corporate-card and expense-management combination addresses a real problem: making company spending easier to understand while it is still current.
My strongest recommendation is to establish the rules before asking the team to use the app. Define what a useful expense explanation looks like, clarify which purchases belong in the workflow, and test the routine with realistic examples. Those steps will do more for the quality of the results than simply installing the app across every phone.
The main friction is that structure requires participation. Employees must provide meaningful context, managers must review it consistently, and finance staff must keep the process aligned with the organization’s broader records. If those responsibilities are ignored, the app can become another inbox rather than a solution.
For a business that has outgrown informal card tracking, I would recommend giving it serious consideration. Its free price and Everyone rating make it approachable, while its current version, 4.0.17, supports a modern mobile environment. Just remember that the minimum operating-system requirement is iOS or Android 12 or later, so older company devices may need attention before rollout.
My final view is simple: this is most valuable when a team treats expense capture as a daily habit, not an end-of-month rescue mission. If that describes your business, BILL Spend & Expense can provide a clearer center for corporate spending. If you only need personal budgeting or occasional reimbursement, a simpler alternative will probably feel more natural.
BILL Spend & Expense (Divvy) FAQ
What is BILL Spend & Expense (Divvy), and who is it designed for?
BILL Spend & Expense, formerly known as Divvy, is a business spending and expense-management app designed for companies, finance teams, managers, and employees. It helps organizations issue and manage corporate cards, set spending limits, track transactions, organize receipts, and monitor budgets. It is primarily intended for businesses using BILL’s financial platform rather than for personal budgeting or everyday individual expenses.
Can employees use the app to submit receipts and manage business expenses?
Yes. Employees can generally use the mobile app to capture receipts, review card transactions, add notes or expense details, and submit spending information for approval. This can reduce paperwork and make it easier for finance teams to match purchases with transactions. The exact workflow depends on the company’s account configuration, approval policies, permissions, and whether the employee is using a BILL corporate card or another supported expense process.
Does BILL Spend & Expense provide corporate cards and spending controls?
The platform is built around business spending control and may provide corporate card features for eligible organizations. Administrators can typically create budgets, assign spending limits, define categories or policies, and monitor activity as purchases occur. These controls can help prevent unauthorized spending and improve visibility, although available card products, limits, approval rules, and eligibility may vary according to the company’s BILL plan, account status, and region.
Is BILL Spend & Expense free to download and use?
Downloading the BILL Spend & Expense mobile application may be free, but access to its business features is connected to a company’s BILL account and service agreement. Organizations may pay subscription, card, processing, or other applicable fees depending on their plan and usage. Employees normally do not choose the pricing themselves, so businesses should review current BILL pricing, terms, and eligibility before adopting the platform.
Is my financial and expense information secure in the app?
BILL Spend & Expense handles sensitive business information, including transaction data, receipts, employee details, and spending records, so security is an important consideration. The app may include account authentication, permission controls, encrypted connections, and administrative oversight, but no online service can eliminate every risk. Users should keep the app updated, use strong unique credentials, protect their device, and report suspicious activity promptly.